 Written and reviewed by Emily Daza, licensed health insurance advisor, NPN 21284721 · Updated November 2, 2026
How do construction workers in Florida get health insurance?
It depends on how you're paid. A W-2 employee may get a group plan if the company offers one; Florida law requires workers' comp on construction jobs, not health insurance. 1099 subcontractors and contractors who own their business buy their own plan: a private plan or an ACA Marketplace plan. Workers' comp only pays for job injuries, so it never covers a weekend accident, an illness or your family. Emily Daza quotes private PPO plans for healthy tradespeople.
Why health insurance is easy to put off in the trades
- You have a workers' comp exemption on file for your LLC and assumed that meant you were covered. It means the opposite.
- You went from W-2 at a big contractor to 1099 sub, and the group plan stayed behind with the old job.
- Work doubles after a hurricane and dries up in a slow summer, so a monthly bill you can't predict feels risky.
- You hurt your back moving furniture on a Sunday, and comp won't touch it because it didn't happen on the job.
- Your wife and kids need a pediatrician and a dentist, not a policy that only covers you on a roof.
- Half your crew speaks Spanish first, and nobody has ever explained a deductible to them in their language.
How Emily helps people who build, fix and maintain South Florida
- Private PPO plans you own. The plan stays with you when you change contractors, go from W-2 to 1099 or open your own company.
- Built for healthy, working people. Emily focuses on private PPO plans for people in good health who want a wide network and a plan that isn't tied to an employer.
- Quotes outside office hours. By phone, text or WhatsApp at 954-695-4250, before you head to the job or after you pack the truck.
- Explained in Spanish or English. Emily was born in Colombia and works in both languages, so you and your family can ask everything you need to.
- Honest about ACA plans. Emily does not sell ACA plans. If you have a pre-existing condition or qualify for a large subsidy, she'll point you to HealthCare.gov.
- Health insurance only. Emily does not sell workers' comp, general liability, commercial auto or any other business insurance. For those, talk to a commercial insurance agent.
Is workers' comp the same as health insurance?
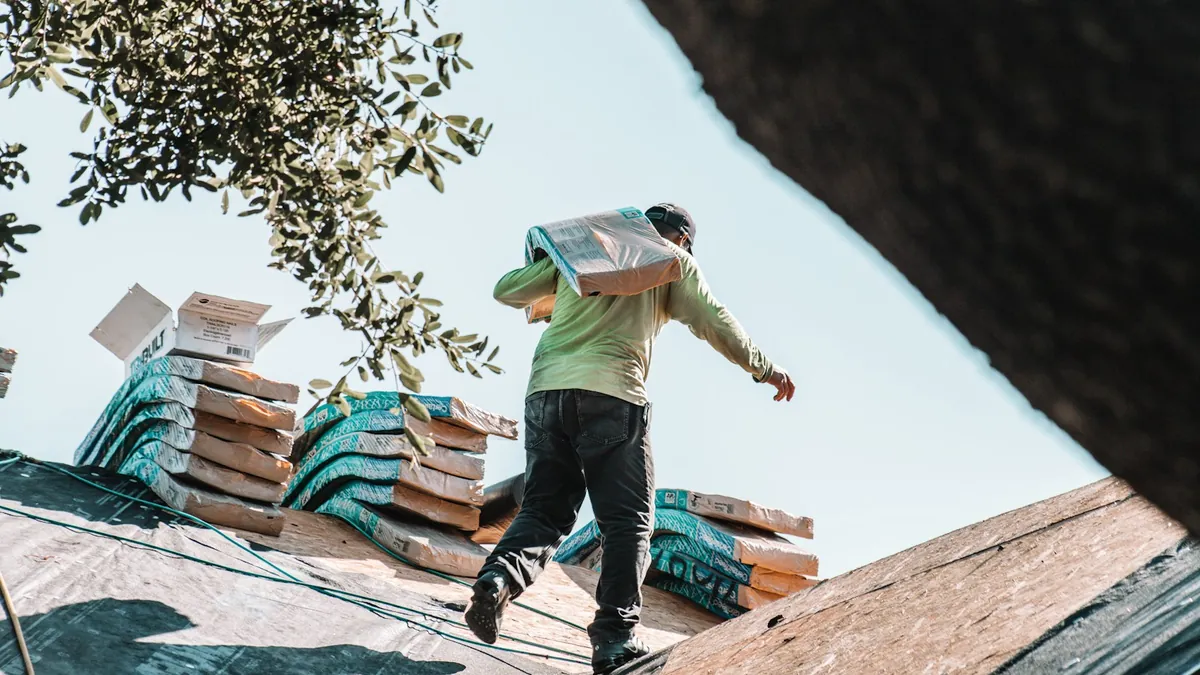
No, and this is the most common mix-up in the trades. In Florida, construction employers with even one employee must carry workers' compensation, and that includes owners who are corporate officers or LLC members unless they file an exemption. Source: Florida Division of Workers' Compensation Workers' comp exists to pay medical care and part of lost wages when someone is hurt or gets sick because of the job.
That is all it does. It doesn't pay for the flu, a kidney stone, high blood pressure, a car accident on the way home from the supply house, a broken wrist from weekend soccer or your daughter's ear infection. It doesn't cover your spouse or kids at all. Comp covers the worker for the work; health insurance covers the person, everywhere else.
So even a crew with perfect comp coverage can be one bad diagnosis away from a hospital bill. A contractor who shows a general contractor a comp certificate has proved one thing: that job injuries are handled. Everything else needs a health plan.
The owner with a comp exemption: the person most often uninsured
Florida lets up to three officers of a construction corporation or LLC (or group of affiliated companies) elect to be exempt from workers' comp. Each officer must own at least 10% of the company, the company must be active with the Florida Division of Corporations, and the application costs $50. Source: Florida Division of Workers' Compensation The certificate is valid for 2 years, and the law is blunt about the trade-off: an officer who elects the exemption is not entitled to comp benefits. Source: Florida Statutes §440.05
Many small contractors take the exemption to keep costs down and win bids, which can make sense for the business. The catch is personal. If you're exempt and you also have no health plan, then a fall from a ladder at work, a heart problem at home or a cancer diagnosis is entirely on you. You are the one person in the company that no policy covers.
If you hold an exemption, put a health plan on the same calendar: when you renew the exemption every two years, check your health coverage too. A private PPO plan covers you on and off the job, and it isn't tied to whether the company carries comp for you.
W-2 employee, 1099 subcontractor or business owner: where does your coverage come from?
Construction laborers and helpers alone held about 1.7 million jobs in 2025, with a median pay of $46,680 a year. Source: BLS Add electricians, plumbers, HVAC techs, roofers and landscapers, and how each one gets health insurance comes down to how they're paid.
A W-2 employee works for a contractor that directs the work. If the company offers a group health plan, that's usually the first option, and it ends with the job. Florida requires comp for these workers, not health insurance. A 1099 subcontractor is treated as an independent business, so nobody offers a health plan. The IRS looks at the whole relationship and how much the company has the right to direct and control the work, not just the label on the paperwork. Source: IRS
On the comp side, if a sub has no coverage, the general contractor is liable for that sub's employees and must ask subs for proof of coverage or an exemption certificate. Source: Florida Statutes §440.10 Nothing like that exists for health insurance. A contractor who owns the business buys coverage for themselves and their family, the same way any self-employed person does. Health insurance for 1099 workers in Florida.
Hurricane season, rebuild booms and income that comes in waves
Atlantic hurricane season runs from June 1 to November 30, and in South Florida a busy storm year can mean months of roof, window, drywall and electrical work, followed by slow stretches. That swing matters when you pick a plan.
ACA Marketplace subsidies are based on the income you estimate for the year, and you're expected to update it when it changes. Source: HealthCare.gov If you earn more than you estimated, you may have to pay back part of the subsidy at tax time. Source: HealthCare.gov For a contractor whose year depends on the weather, that estimate is a guess. A private PPO plan isn't priced on your income, so a boom year doesn't change what you owe.
Timing matters too. ACA plans can be bought during Open Enrollment, which starts November 1, or within 60 days of a qualifying event such as losing job-based coverage. Source: HealthCare.gov Many private plans can be applied for during the year. If you just went from W-2 to 1099, don't wait for the slow season to decide.
Heat, heavy work and injuries that don't happen on the job
Construction laborers have one of the highest rates of injuries and illnesses of all occupations, and they often work outdoors in all weather. Source: BLS OSHA lists roofing and other outdoor construction among the settings where heat illness happens, and says new workers need several days to adjust to the heat. Source: OSHA
Job injuries go to comp. But years of heat, lifting and kneeling show up off the clock too: a back that gives out at home, a knee that needs an MRI, blood pressure that creeps up, dehydration that turns into a kidney problem. When it's unclear whether something started at work, having health insurance means you're not stuck in the middle without care.
Your body is your business. Before you buy, ask whether a plan covers preventive visits, urgent care, imaging and the prescriptions you take, and check that the doctors near your home in Hialeah, Pembroke Pines or West Palm Beach are in the network. PPO vs HMO in Florida.
Covering your family, and a word for crews
Workers' comp never covers a spouse or children, so for most tradespeople the real question is a family plan. Many of the private PPO plans Emily quotes can include your spouse and kids on one policy, so the whole household has one network and one card. Family health insurance in Florida.
If you run a crew, you can't buy individual health plans for your 1099 subs, and you shouldn't promise coverage you don't control. What you can do is point people to good information. Many crews across Miami-Dade, Broward and Palm Beach are Spanish-speaking, and a worker who understands a deductible in Spanish is far more likely to get covered. Share this guide in either language, or have them call Emily directly.
If you have W-2 employees and want to offer something, ask Emily about the options for owners and small teams on the small business page.
Can you deduct your health insurance as a contractor?
If you're self-employed, you may be able to deduct what you pay for health insurance for yourself, your spouse and your dependents. The IRS self-employed health insurance deduction is figured on Form 7206. Source: IRS It can't be taken for any month you were eligible for an employer-subsidized plan, including through a spouse's job, and it's limited by your business's net earnings. Source: IRS
That last rule matters in construction: in a year when the business shows little profit on paper, the deduction can shrink with it. Emily doesn't give tax advice; ask your accountant or tax preparer how it applies to you. HealthCare.gov also explains coverage options for the self-employed. Source: HealthCare.gov
Workers' comp vs ACA plan vs private PPO: what each one covers
Three different things that people in the trades often confuse.
| Workers' comp | ACA Marketplace plan | Private PPO plan | |
|---|---|---|---|
| What it pays for | Medical care and part of lost wages for job injuries and illnesses | Medical care on and off the job | Medical care on and off the job |
| Covers your family | No | Yes, if you add them | Yes, if you add them |
| Who must have it | Construction employers with 1+ employee, unless an officer is exempt | No one is required to in Florida | No one is required to |
| Health questions | No | No; you can't be turned down for health | Usually yes; approval depends on your health |
| Price tied to your income | No (based on payroll and trade) | Subsidies are based on estimated income | No |
| When you can buy | When you hire employees | Open Enrollment or a qualifying event | Often during the year |
| Who helps you | A commercial insurance agent | HealthCare.gov | Emily Daza (healthy applicants) |
How it works
- Ten-minute call, text or WhatsApp. Your ZIP, who needs coverage, how you're paid (W-2, 1099 or your own company) and whether you hold a comp exemption.
- Emily checks the fit. Your health and situation, so she knows whether a private PPO fits or an ACA plan through HealthCare.gov is the better route.
- Options side by side. Monthly premium, deductible and whether your doctors near home are in network, in English or Spanish.
- Enroll, then keep it from job to job. Emily stays your contact and reviews your plan every year, busy season or slow.
Who is behind this guide?
- Emily Daza, licensed health insurance advisor, NPN 21284721, licensed in 31+ states.
- Rated 5.0 on Google by real clients, and has helped thousands of people find coverage.
- $2.3M+ in sales, all 4 Hope Awards and the Beacon Award, top 3 in her region, leading a team of 8.
- Born in Colombia and fluent in Spanish, working from Daza Health, 8050 SW 10th St, Plantation, FL 33324. Call, text or WhatsApp 954-695-4250.
Keep exploring
- Coverage: Self-employed · Family plans · Small business · Losing employer coverage
- Guides: Private vs ACA · Open Enrollment · FAQ · All guides
- More articles: Health insurance for 1099 workers · Family health insurance in Florida · PPO vs HMO in Florida · Truck drivers
- Near you: Miami · Hialeah · Fort Lauderdale · West Palm Beach · En español